Inherited Roth IRAs: What Happens After the Climb
by Corey Sunstrom, CFP®
Director of Financial Planning
Hiking is a choice, which is something I occasionally have to remind myself of when I’m several hours into a long, arduous walk with friends, my legs are beginning to object, and I’m wondering why I voluntarily decided that climbing a particular mountain was a worthwhile way to spend a day. There is something inherently ridiculous about hiking when you stop to think about it. Most of our adventures amount to spending an enormous amount of time and energy finding the most inconvenient possible way to return to the exact same parking lot we left that morning, and somehow, we consider that a successful outcome.
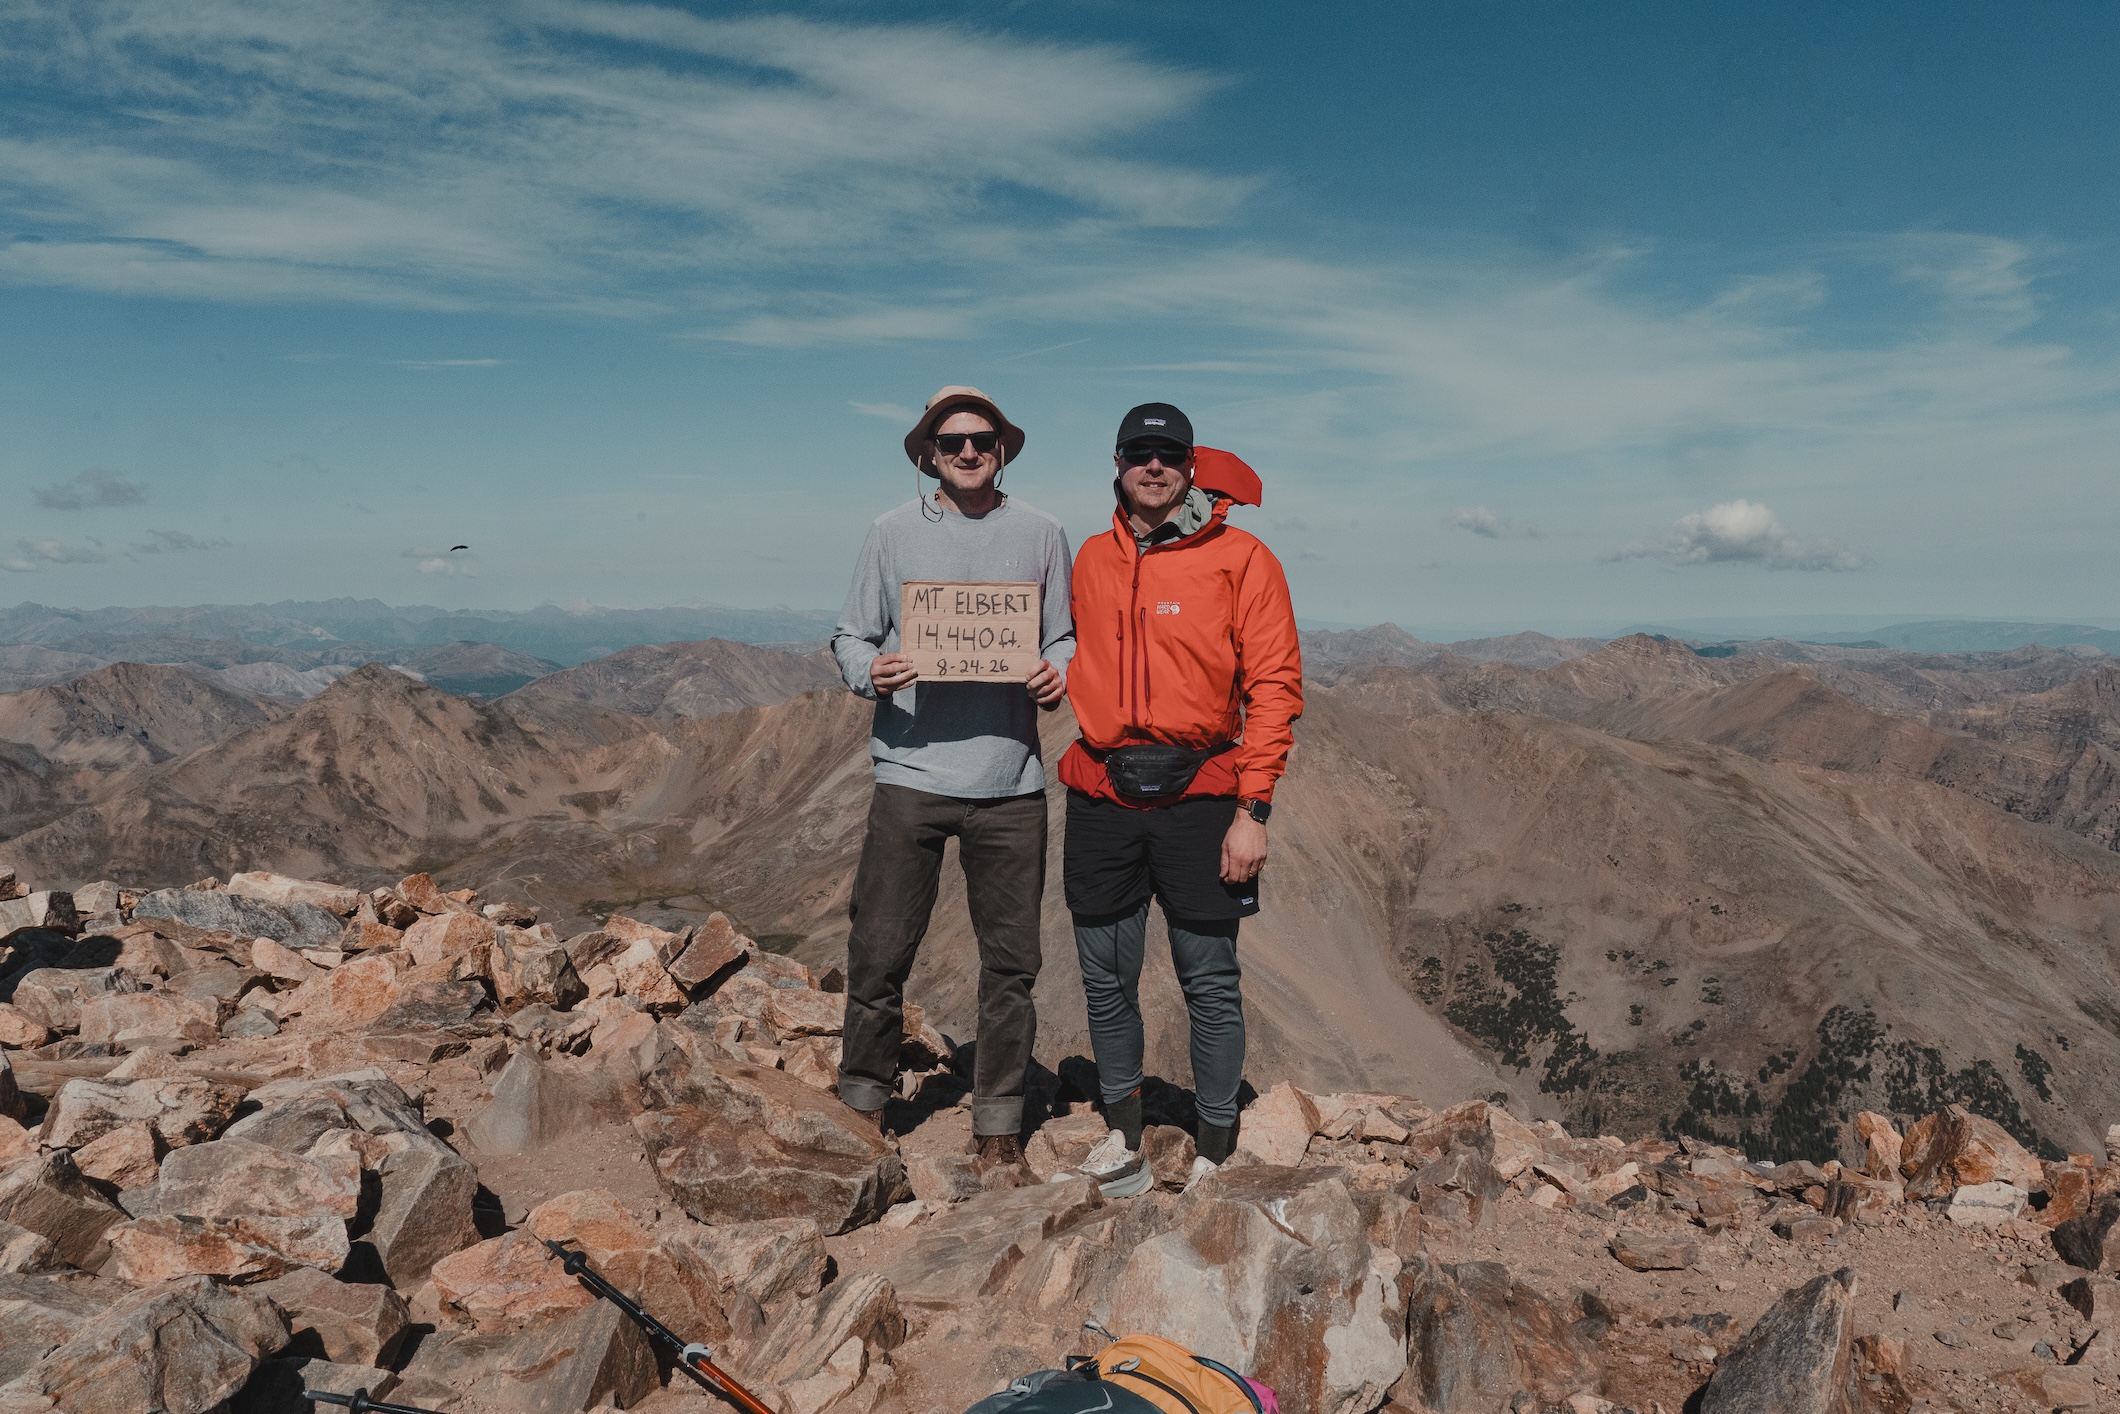
This was especially apparent when my good friend Eli texted me asking if I wanted to hike Mt. Elbert, the highest point in Colorado. A few weeks later in August, I found myself standing at the trailhead at four o’clock in the morning.
To be fair, I generally know what I’m getting myself into. I just have a remarkable ability to filter out the physical part of hiking when I’m planning it. When the trip is still comfortably several weeks away, I’m thinking about the accomplishment, the scenery, the views from the summit, and how satisfying it will feel to have done something difficult. I spend considerably less time imagining what it will feel like to climb for hours while my lungs negotiate with me at altitude and my knees prepare their case against me for the descent. That selective memory is probably a large part of why I continue signing up for these things.
Mt. Elbert was no different. We started before sunrise and made quick progress through the lower part of the mountain in the dark, with our headlamps illuminating only a small patch of trail in front of us while the rest of Colorado remained hidden. As we climbed, the sun slowly began to appear over the horizon and the landscape revealed itself one ridge at a time, which is one of those moments that reinforces the idea that getting out of bed at an unreasonable hour was somehow worth it.
For the first several miles, we moved at a good pace, but as the trail pushed higher and we climbed above 12,000 feet, things began to slow down considerably. Conversations got shorter, breathing became something you had to think about rather than something your body simply handled on its own, and the mountain started collecting payment for all those sweeping views. Mt. Elbert also has a charming habit of making you believe you are nearly finished. You crest a ridge, see what appears to be the summit ahead, and convince yourself that the hard part is essentially over, only to reach it and discover another climb waiting beyond it. Then the mountain does it again.
Eventually, though, there were no more false summits left, and about four hours after we started, we reached the top. The sun was out, the temperature was somewhere around a chilly 45 degrees, which felt magnificent after months of oppressive Southern summer, and the views seemed to stretch endlessly in every direction. For a little while, we stood there taking it all in and congratulating ourselves for having voluntarily walked to a place where the air was thinner, the temperature was colder, and getting back to civilization would require several more hours of walking.
That last part is easy to ignore when you are focused on reaching the summit, but every hike has a return trip, and the descent is usually a very different experience from the climb. Different muscles begin to ache, your attention shifts toward footing and tired legs, and the goal that motivated you all morning has already been accomplished. On the way up, I tend to think almost entirely about reaching the top, moving forward, and finishing what I came there to do. On the way down, my ambitions become considerably less noble and increasingly food-oriented.
At first, I’m thinking about how many miles are left. After a while, I start thinking about the cold beer waiting somewhere at the end of the trail. A few miles later, I have selected the beer and begun constructing the burger that should accompany it. Eventually I am considering toppings, sides, and whether fries or onion rings would be the more responsible choice after several hours of hiking, as though personal responsibility has anything to do with the decision at that point. By the final stretch, I have usually designed an entire post-hike meal in my head, sometimes at a restaurant I have not yet confirmed exists.
All of which is to say that the hike down is not always the enjoyable part. The views are still there, and you are still standing in one of the most beautiful places you could reasonably hope to be, but the experience has changed. The objective is different, your body is reacting differently, and the mindset that carried you toward the summit is not necessarily the one that gets you comfortably back down. What felt exciting and purposeful on the climb can start to feel tedious once the accomplishment is behind you and the only remaining task is getting yourself back to where you started.
Eventually the trees begin to thicken, the grade eases, and somewhere through the woods you catch sight of something that would have been completely unremarkable eight hours earlier: the parking lot.
It is the same parking lot you left that morning, the same patch of gravel you were so eager to walk away from in the dark, but after spending an entire day taking the least efficient route imaginable back to it, it is one of the most beautiful things you have ever seen.
I think there is something familiar in the way we tend to approach our finances. Most of the attention goes toward the climb. We spend decades saving, investing, contributing to retirement accounts, converting money to Roth when the opportunity makes sense, and generally trying to push the number higher. There are benchmarks along the way and eventually some version of a summit, whether that means retirement, financial independence, or simply reaching the point where you know you have accumulated more than you are likely to spend.
What happens after that tends to receive far less attention, even though the rules can change considerably once money begins moving in the other direction. That is particularly true when retirement assets eventually pass to someone else. A Roth IRA can spend decades quietly compounding without required distributions during the original owner’s lifetime, only to enter an entirely different set of rules when it becomes an inherited Roth IRA. At that point, when the account was inherited and who inherited it become just as important as all the work that went into building it in the first place. The climb matters, of course, but there is quite a bit of planning left once you reach the top.
Inherited IRAs have somehow become one of the more confusing corners of retirement planning, which is impressive considering the basic premise sounds pretty simple. Someone owns an IRA, they pass away, and the person named as beneficiary inherits it. Unfortunately, the rules governing what happens next depend on several details, and one of the most important is a date that has nothing to do with the beneficiary at all: when the original account owner died.
That date matters because Congress significantly changed the inherited IRA rules beginning in 2020. As a result, two adult children could inherit virtually identical Roth IRAs from their parents, with the same account balance and the same investments, and have completely different distribution requirements simply because one parent died in 2019 and the other died in 2020. For families who have accumulated substantial retirement assets, understanding that difference is important not only for avoiding an RMD mistake, but also because it highlights just how valuable a Roth IRA can become when the goal shifts from funding your own retirement to eventually leaving money to the next generation.
If the Roth IRA Was Inherited Before 2020
For an original account owner who died in 2019 or earlier, we are generally dealing with the old inherited IRA rules. Under that system, an individual beneficiary could typically take required distributions based on his or her own life expectancy, a strategy commonly referred to as the “stretch IRA.” A younger beneficiary might have a distribution period that lasted several decades, which meant only a relatively small portion of the inherited account had to come out each year while the remaining balance could continue growing inside the Roth.
Imagine, for example, a 45-year-old inheriting a sizable Roth IRA from a parent in 2018. That beneficiary did not have the option of simply ignoring the account indefinitely, because annual distributions generally had to be taken. But those distributions could be spread across the beneficiary’s life expectancy rather than forcing the account to be emptied within a short period of time. For a Roth IRA, where qualified distributions are generally income-tax-free, that created the opportunity for decades of additional tax-free compounding after the original owner’s death.
The important thing to understand is that Congress changing the rules in 2020 did not suddenly pull these older inherited accounts into the new system. If the original owner died before 2020 and the beneficiary was properly operating under the prior life-expectancy rules, those older rules generally continue to govern the account. So if you have been taking annual RMDs from an inherited Roth for years, the arrival of the SECURE Act did not automatically reset your distribution schedule.
If the Roth IRA Was Inherited in 2020 or Later
For most adult children and other nonspouse beneficiaries inheriting from someone who died after December 31, 2019, the SECURE Act replaced the lifetime stretch with what is now known as the 10-year rule. Instead of spreading distributions across the beneficiary’s life expectancy, the inherited Roth generally must be completely distributed by December 31 of the tenth year following the year of the original owner’s death. If a parent dies in 2026, for example, an adult child who falls under the standard 10-year rule would generally have until December 31, 2036 to empty the account.
Where this gets confusing is that people have heard a tremendous amount over the past few years about annual RMDs being required during that 10-year period. That can be true for certain inherited traditional IRAs because the rules depend in part on whether the original owner had already reached his or her required beginning date. Roth IRAs are different. The original Roth owner does not have lifetime RMDs, and for inherited-RMD purposes the IRS treats that owner as having died before the required beginning date. As a result, under current IRS guidance, a typical adult child inheriting a Roth IRA under the 10-year rule generally does not have to take an annual distribution in years one through nine. The requirement is that the account be empty by the end of year ten.
That distinction creates considerably more flexibility than the phrase “10-year rule” might suggest. The beneficiary does not generally have to withdraw ten percent per year, nor is there generally a requirement to divide the account into ten equal installments. If the money is not needed, the beneficiary may be able to leave it invested for most or all of that period, allowing the account to continue compounding inside the Roth before ultimately distributing the balance by the deadline. Depending on the size of the account, the investment return, the age of the beneficiary, and applicable Roth holding-period rules, those additional years can matter quite a bit.
There Are Still Exceptions
The 10-year rule is broad, but it does not apply identically to everyone. Congress preserved more favorable treatment for a category called “eligible designated beneficiaries,” which includes surviving spouses, certain disabled or chronically ill beneficiaries, the original owner’s minor child, and beneficiaries who are not more than ten years younger than the original owner. Depending on the circumstances, these beneficiaries may be able to use life-expectancy distributions instead of immediately falling under the standard 10-year framework.
Spouses deserve particular attention because they generally have the most flexibility. A surviving spouse can often elect to treat an inherited Roth as his or her own Roth IRA, allowing the account to continue under the normal Roth rules without lifetime RMDs. Minor children of the original owner also receive special treatment for a period of time, although the 10-year rule generally begins once the child reaches age 21. These exceptions are why I am hesitant whenever someone tells me they have “an inherited IRA” and immediately asks when the RMD is due. Before answering that question, we need to know when the owner died, who inherited the account, and exactly what type of retirement account we are dealing with.
Why the Roth Can Be Such a Valuable Legacy Asset
This is where inherited Roth planning becomes much more interesting than simply memorizing distribution rules. Most of us are introduced to Roth IRAs as retirement vehicles: pay the tax now, allow the money to grow, and eventually take qualified withdrawals tax-free. That is certainly valuable, but for families who have accumulated more retirement assets than they are likely to spend, the Roth may serve another purpose. It can become an estate-planning asset that may transfer a pool of money to the next generation without transferring the same embedded income-tax liability that comes with a traditional IRA.
Consider what can happen over the life of that account. A parent may spend years strategically converting traditional IRA dollars into a Roth, paying the income tax from other assets and allowing the Roth to continue growing without being forced to take RMDs. If the parent never needs those dollars, the child can inherit the Roth and, under today’s rules, may then have another 10-year window before the account has to be completely distributed. Assuming the applicable Roth holding-period requirements have been satisfied, the distributions to the beneficiary are generally income-tax-free. The parent paid the tax once, the account potentially compounded for years or decades afterward, and the beneficiary may receive another extended period of tax-free growth before ultimately taking the money out.
That becomes especially compelling when the people inheriting these assets are in their 40s, 50s or 60s and are already in their own peak earning years. A $1 million traditional IRA and a $1 million Roth IRA may look identical on a balance sheet, but economically they are not the same asset. The traditional IRA carries an income-tax liability that eventually has to be settled as money comes out. The Roth, assuming the requirements have been met, does not carry that same income-tax liability. When substantial wealth is moving from one generation to another, that distinction can be meaningful.
The Planning Question Is Bigger Than the RMD
None of this means everyone should convert every available dollar to Roth or refuse to spend Roth assets during retirement. There are too many other variables involved for a rule that simple. Traditional retirement accounts can be particularly attractive assets to leave to charity because a qualified charitable organization generally does not face the income-tax problem that an individual beneficiary would. Appreciated investments held in a taxable account may receive a step-up in cost basis at death under current law, potentially eliminating substantial unrealized gains. Roth assets, meanwhile, may be particularly attractive to evaluate for children or other individual beneficiaries.
For clients who have accumulated enough wealth that some of it is likely to outlive them, I think that changes the way we should approach retirement income planning. We still care about where this year’s spending comes from, but we should also be looking several moves ahead and asking where each account is ultimately headed. That can influence which accounts we spend first, when Roth conversions make sense, how aggressively we convert, and even which beneficiaries should receive which assets.
The inherited Roth rules are complicated enough that getting the dates and beneficiary classifications right matters. But underneath all of those rules is a much simpler idea. Once you are reasonably confident that you will not spend everything you have accumulated, the question is no longer just how to make your retirement assets last for your lifetime. It is how to leave the right assets, to the right people, in the most useful form possible. For many families, a well-funded Roth IRA may be an important asset to evaluate as part of a coordinated legacy and tax-planning strategy.
Safeguard Your Finances With Pro Guidance
Want to learn more about Inherited IRA’s and how they can impact your finances? You don’t have to navigate this complex terrain alone. Working with an advisor can help you understand your options.